
When shipping goods from China to the UAE, choosing between mainland delivery, free zone receiving, and re-export arrangements can affect far more than the final delivery address.
The decision determines which customs procedures apply, who can legally receive the shipment, what documents are needed, and whether additional duty, VAT, storage, or local transportation arrangements may be required.
For example, a container arriving at Jebel Ali Port for delivery to a Dubai mainland distributor may follow a different customs process from the same container entering a warehouse in Jebel Ali Free Zone (JAFZA). If the goods are later transferred from JAFZA to mainland or re-exported to another country, further procedures may be necessary.
This guide explains how these arrangements work for commercial shipments from China, with practical comparisons covering JAFZA, Dubai South, KEZAD, customs responsibilities, VAT Designated Zones, and warehouse delivery planning.
Quick Answer: Mainland, Free Zone or Re-export Delivery?
Choose UAE mainland delivery when goods are intended for domestic sale or use and an eligible importer can arrange clearance. Choose free zone receiving when an authorized consignee will store, handle, or redistribute the cargo under the applicable customs regime. For re-export shipments, confirm onward declarations and destination-country requirements. Free zone status alone does not guarantee VAT exemption or mainland clearance.
Before booking, confirm three details: the exact receiving address, the entity responsible for customs procedures, and whether the goods will be used in the UAE or shipped onward.
Mainland Delivery, Free Zone Receiving, Designated Zones and Re-export: What Is the Difference?
These terms describe different aspects of a shipment. Understanding their boundaries is essential because the physical destination, customs status, and tax treatment do not always align.
What Is UAE Mainland Delivery?
Mainland delivery generally refers to goods that are imported for use, sale, installation, or distribution within the UAE domestic market.
Common destinations include:
- A wholesale distributor’s warehouse in Dubai.
- A retail distribution center in Sharjah.
- A factory or assembly facility in Abu Dhabi.
- A construction or equipment installation site.
- A warehouse supplying UAE domestic customers.
For standard commercial imports, the responsible importer or authorized customs representative must complete the applicable import procedures.
These may involve customs registration, product classification, supporting commercial documents, regulatory approvals, customs duty, and VAT accounting or payment.
Port arrival is not the same as mainland customs clearance.
Goods discharged at Jebel Ali Port, Khalifa Port, or another UAE gateway remain subject to the applicable customs and cargo-release procedures until the required authorizations are completed.
The international carrier, terminal operator, customs authority, and local delivery provider may each have separate release requirements.
What Does Free Zone Receiving Mean?
Free zone receiving means transporting goods to an eligible company or facility within a UAE free zone under the relevant customs and operating arrangements.
Depending on the facility’s permissions and capabilities, the goods may be:
- Stored before final customer allocation.
- Consolidated with inventory from other suppliers.
- Inspected, sorted, labeled, or repacked.
- Prepared for onward international distribution.
- Held before partial release into UAE mainland.
A free zone arrangement may help a regional distributor manage inventory without immediately committing every product to the UAE domestic market.
However, free zone entry is not equivalent to clearance for unrestricted mainland use.
The consignee, warehouse operator, and customs representative must confirm the applicable movement and receiving procedures.
What Is a VAT Designated Zone?
A VAT Designated Zone is a specific area recognized under UAE VAT legislation that meets prescribed statutory and operational conditions.
It is not automatically the same as a free zone established for commercial or industrial activities.
According to the UAE Federal Tax Authority (FTA), a qualifying VAT Designated Zone must be included in the applicable official list and satisfy requirements concerning geographic boundaries, security, customs controls, and procedures for handling goods.
The FTA’s October 2026 clarification, Free Zones and Designated Zones for Tax Purposes (TAXP010), emphasizes that tax classifications must be considered separately.
Even where a warehouse is located within a qualifying VAT Designated Zone, special VAT treatment applies only to transactions meeting the relevant conditions.
A free zone trade license does not independently establish that every supply, service, or goods movement is outside the scope of VAT.
What Is Re-export Through the UAE?
Re-export involves goods that have entered the UAE and are subsequently shipped to another country under an applicable customs procedure.
For example, a trading company may receive equipment from China into a UAE free zone warehouse, hold the equipment temporarily, and later send it to a customer in Kenya.
Re-export can also follow earlier mainland importation, although the procedures and possible tax consequences may differ.
It is important to distinguish re-export from customs transit, where goods may move through the UAE under a separate customs arrangement.
Re-export describes an onward goods movement. It is not another name for free zone delivery.
Mainland vs Free Zone vs Re-export: Which Arrangement Fits Your Cargo?
The appropriate arrangement depends primarily on the goods’ intended final use.
| Comparison Factor | Mainland Import | Free Zone Receiving | Free Zone Receiving and Re-export |
|---|---|---|---|
| Primary purpose | UAE domestic sale or use | Storage, handling, inventory allocation | Distribution to another country |
| Typical receiver | Eligible mainland importer | Authorized free zone business or warehouse | Authorized receiving entity and onward exporter |
| Customs procedure | Domestic import clearance | Applicable free zone entry procedure | Inbound entry and outbound customs procedure |
| Duty treatment | Depends on the applicable import regime | Depends on customs status and later movements | Depends on the original and onward movement |
| VAT treatment | Applicable domestic import and supply rules | Depends on zone qualification and transaction | Depends on the transaction and supporting evidence |
| Final delivery | Domestic warehouse or project site | Authorized zone facility | Free zone warehouse followed by export handover |
| Main operational risk | Missing importer registration or approvals | Incorrect consignee or receiving arrangement | Incomplete inventory and exit records |
These are common logistics arrangements rather than mutually exclusive legal classifications. Goods entering a free zone may subsequently be imported into mainland or re-exported.
When Is Mainland Import the Better Option?
Direct mainland import is generally appropriate when the goods are already committed to a UAE buyer or intended for domestic consumption.
For example, a Dubai wholesaler purchasing electrical accessories from Shenzhen may prefer to arrange import clearance and deliver the goods directly to its local distribution warehouse.
If no intermediate storage or overseas distribution is needed, routing the same shipment through a free zone warehouse first may create additional handling and transport costs.
Before choosing mainland delivery, the buyer should confirm that an eligible importer and any necessary customs or product approvals are available.
When Is Free Zone Storage More Appropriate?
Free zone storage may be useful when the cargo owner needs to hold goods before deciding which market will receive them.
A regional distributor might import products from several Chinese manufacturers and combine them into a single UAE warehouse inventory.
Orders can then be allocated to UAE customers or overseas markets according to demand.
This flexibility must be weighed against warehouse storage fees, inventory handling, customs administration, and subsequent transport costs.
When Is Re-export Planning Necessary?
Re-export planning is important when goods are intended to leave the UAE after storage or another authorized goods movement.
The cargo owner should identify:
- The destination country.
- The entity responsible for the onward export.
- The goods’ original customs status.
- The documents required for the outward movement.
- The evidence necessary to demonstrate that the goods left the UAE.
The onward destination may have separate import licensing, product certification, customs valuation, and taxation requirements.
Where the destination is another GCC country, the applicable customs arrangements should also be checked rather than assuming the procedure is identical to exports outside the GCC.
JAFZA, Dubai South and KEZAD: Which UAE Destination Fits Your Shipment?
Major UAE logistics and industrial developments offer different receiving arrangements.
However, the name of the logistics hub alone is not enough to determine how a particular shipment should be cleared and delivered.
JAFZA: Port-Linked Storage and Regional Distribution
Jebel Ali Free Zone (JAFZA) is located alongside Jebel Ali Port in Dubai.
Its connection to a major international seaport makes it relevant to businesses importing containerized goods from China for storage, consolidation, or regional distribution.
A typical planning route might be:
China Export Port → Jebel Ali Port → Applicable Free Zone Entry → JAFZA Warehouse
This arrangement may suit companies holding trading inventory, equipment, spare parts, or goods awaiting allocation to regional customers.
Before shipping, confirm:
- The legal name of the receiving company.
- Whether the company or warehouse is authorized to receive the goods.
- The applicable free zone entry procedure.
- Who will arrange carrier release and customs documentation.
- Whether the delivery vehicle requires advance access authorization.
- Whether the warehouse can unload the cargo.
JAFZA has controlled gate-access arrangements, including the Tasreeh system. The receiving entity should confirm the current access requirements for the actual vehicle, driver, and delivery.
For full-container-load shipments, clarify whether the container will be unloaded at the warehouse and who is responsible for its empty return.
A container may be available for pickup from the port while the receiving warehouse is not yet ready to accept it.
Dubai South: Airport Logistics and Distribution
Dubai South includes logistics facilities associated with the wider transport network around Al Maktoum International Airport (DWC).
Its Logistics District supports activities such as international cargo handling, warehousing, inventory management, and distribution.
It can be relevant to companies using air freight, contract logistics, or regional fulfillment arrangements.
However, the wider Dubai South development includes facilities with different operating characteristics, including bonded and non-bonded access arrangements.
Therefore, importers should not assume that every Dubai South address has identical customs status or VAT treatment.
Before arranging delivery, confirm the exact building and receiving entity, whether the facility can accept the goods under the proposed customs procedure, and whether mainland import clearance is necessary.
For VAT purposes, the official Designated Zones list identifies particular qualifying areas, including Dubai Aviation City. This does not establish that every facility marketed as part of Dubai South automatically qualifies for the same treatment.
KEZAD: Industrial and Logistics Receiving in Abu Dhabi
Khalifa Economic Zones Abu Dhabi (KEZAD) includes industrial and logistics facilities connected to Abu Dhabi’s transport and manufacturing network.
KEZAD offers both Free Zone and Domestic Economic Zone arrangements.
This distinction is particularly important for shipments arriving through Khalifa Port.
For example, machinery imported for installation at a domestic industrial facility may need a different import and delivery arrangement from spare parts entering an eligible free zone warehouse for later regional distribution.
Importers should verify which jurisdiction applies to the exact receiving location.
They should also confirm whether the appointed customs broker and receiving company can handle the intended declaration and physical handover.
| Location | Typical Logistics Connection | Suitable Cargo Flow | Critical Verification |
|---|---|---|---|
| JAFZA | Jebel Ali Port | Container storage and regional distribution | Free zone entry, consignee and gate access |
| Dubai South Logistics District | DWC and Dubai logistics network | Air cargo, warehousing and contract logistics | Exact facility and customs status |
| KEZAD Free Zone | Abu Dhabi logistics and Khalifa Port network | Controlled storage and distribution | Free zone receiving authority |
| KEZAD Domestic Economic Zone | Abu Dhabi industrial network | Domestic industrial or commercial use | Mainland customs arrangements |
| Dubai Mainland | UAE gateway and inland transport | Local distribution or project delivery | Eligible importer and domestic clearance |
Practical rule: Obtain the warehouse’s full address, legal receiving company, and customs instructions before selecting the international shipping route.
Three Illustrative Cargo Flows from China to the UAE
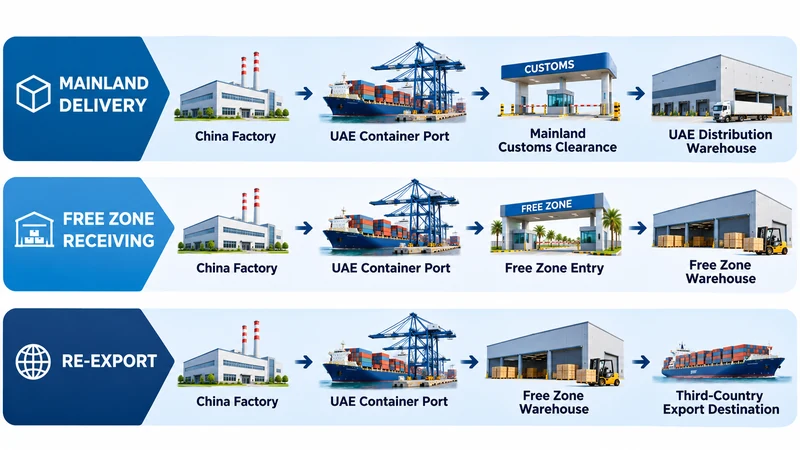
The following examples explain how different shipment arrangements work in practice.
All three are illustrative scenarios, not actual Winsail customer shipments.
Scenario 1: China → JAFZA Storage
Cargo: Commercial inventory sourced from China.
Objective: Store goods in JAFZA before allocating them to UAE or overseas customers.
Illustrative flow:
China Supplier → China Export Clearance → Jebel Ali Port → Free Zone Entry → JAFZA Warehouse → Inventory Storage
Step 1 — Confirm the receiving entity
The cargo owner obtains the warehouse’s exact address and confirms which legal entity will receive the goods.
The receiving party or appointed customs representative verifies the appropriate entry arrangement.
Step 2 — Prepare export documents
The Chinese supplier prepares the commercial invoice and packing list with accurate descriptions, quantities, weights, and values.
The parties confirm the transport document’s consignee and notify-party information before the shipment departs China.
Step 3 — Coordinate arrival and release
Once the cargo arrives at Jebel Ali Port, the relevant parties arrange carrier release, terminal handling, and applicable customs procedures.
A shipping line’s delivery order does not replace customs authorization.
Step 4 — Arrange warehouse entry
The appointed logistics and receiving parties coordinate the permitted movement into JAFZA.
Vehicle access, receiving appointments, unloading capability, and container-return instructions should be confirmed.
Step 5 — Record inventory
The warehouse records the received quantities and relevant product information.
Inventory records should allow the cargo owner to connect stored goods to their original shipping and customs documentation.
Step 6 — Plan subsequent movements
If part of the inventory is later sold to a mainland buyer, an appropriate domestic import procedure may apply.
If stock is shipped to another country, the responsible parties must arrange the applicable export or re-export process.
Key risk: Incorrect consignee details or missing warehouse authorization can prevent delivery even when the international shipment itself has arrived without difficulty.
Scenario 2: China → Dubai Mainland
Cargo: Commercial goods purchased by a Dubai-based distributor.
Objective: Import goods for domestic sale.
Illustrative flow:
China Supplier → International Freight → UAE Port/Airport → Mainland Import Clearance → Dubai Warehouse
Step 1 — Confirm importer eligibility
The UAE buyer identifies the eligible importer and confirms that the necessary customs registration and broker arrangements are available.
Step 2 — Review goods and approvals
The importer or authorized broker checks the product description, HS classification, commercial value, origin information, and applicable restrictions.
Product-specific approvals may be necessary depending on the goods.
Step 3 — Prepare the shipment
The supplier and forwarder coordinate the export documents and international freight booking.
Any discrepancies in legal names, cargo descriptions, or commercial values should be resolved before departure where possible.
Step 4 — Complete customs clearance
The importer or authorized representative submits the applicable declaration.
Customs assesses the documents and may require inspection or additional evidence.
Any relevant duty, VAT, or other release requirements must be addressed.
Step 5 — Arrange final delivery
After the required customs and cargo-release procedures are complete, the goods can move to the buyer’s warehouse.
The receiver confirms the unloading appointment and signs the appropriate delivery records.
Key difference: The goods are intended to enter UAE domestic circulation rather than remain under a free zone storage arrangement.
Key risk: The shipment reaches the destination gateway before the importer has confirmed the customs broker, product approvals, or necessary registration.
Scenario 3: China → UAE Free Zone → Third Country
Cargo: Spare parts sourced from China.
Objective: Hold inventory in a UAE free zone before shipping an overseas customer order.
Illustrative destination: Kenya.
Illustrative flow:
China Supplier → UAE Free Zone Entry → Warehouse Storage → Order Allocation → Re-export Procedure → Kenya
Step 1 — Establish the inbound arrangement
The distributor confirms that the receiving company and warehouse can handle the goods under the intended customs procedure.
Step 2 — Receive and record the shipment
The warehouse accepts the goods and records quantities, product identifiers, and the relevant incoming shipment references.
Step 3 — Allocate the overseas order
When the Kenyan customer places an order, the distributor identifies the products and quantities to be dispatched.
The warehouse must be able to reconcile this allocation with the original inventory.
Step 4 — Prepare outward documentation
The relevant trading and logistics parties prepare the commercial and transport documents required for the new shipment.
The authorized party arranges the applicable UAE export or re-export declaration.
Step 5 — Complete the outward movement
The goods leave the warehouse under the required authorization and are handed over for international transportation.
Step 6 — Retain evidence
The exporter retains relevant customs records, shipment documents, and evidence supporting the goods’ exit from the UAE.
The importer in Kenya must separately meet applicable Kenyan customs, tax, and regulatory requirements.
Key risk: Incomplete stock records or missing exit evidence may create customs and tax complications when the original goods movement is reviewed.
Who Can Receive the Goods and Who Handles Customs Documents?
The physical receiving company is not always the legal importer.
A single shipment can involve several organizations performing different functions.
Consignee, Importer, Broker and Warehouse Operator
The consignee is the party identified on the transport document according to the shipping arrangement.
The customs importer is the entity responsible under the applicable customs procedure.
The customs broker is an authorized representative appointed to perform permitted declaration and clearance activities.
The free zone receiving entity is the business or facility operator eligible to accept the shipment under the relevant zone arrangements.
The warehouse operator handles the physical receipt, storage, inventory control, and agreed handling operations.
The cargo owner may be another company entirely.
These parties can differ, but their roles must be compatible with the applicable law, contractual arrangements, and customs documentation.
For example, a regional distributor may own the goods while an independent warehouse receives them physically.
That warehouse does not automatically become the customs importer merely because its address appears in the delivery instructions.
Documents & Responsible Parties
| Document / Requirement | Typically Prepared or Issued By | Main Responsible Party | Purpose |
|---|---|---|---|
| Commercial invoice | Seller or relevant transaction party | Importer and broker | Identify goods, transaction and value |
| Packing list | Shipper or supplier | Broker, warehouse and forwarder | Confirm packaging and quantities |
| Bill of lading / air waybill | Carrier or authorized issuer | Consignee and relevant transport parties | International carriage and release |
| Delivery order | Carrier or authorized agent | Party arranging cargo release | Carrier-controlled release |
| Customs declaration | Eligible declarant or authorized broker | Importer / exporter as applicable | Declare the relevant customs movement |
| Trade license / customs registration | Registered UAE business and authority | Relevant importer or receiving company | Establish procedural eligibility |
| Free zone entry / delivery advice | Authorized parties under the applicable procedure | Broker and free zone receiver | Support customs-controlled delivery |
| Product-specific permit | Relevant competent authority | Responsible importer or applicant | Meet cargo-specific regulatory conditions |
| Warehouse receiving confirmation | Warehouse operator | Local delivery and receiving parties | Confirm physical receipt |
| Export / re-export evidence | Relevant customs and transport parties | Responsible exporter and records custodian | Support authorized outward movement |
These are common document categories, not a universal mandatory list.
Requirements depend on cargo type, customs jurisdiction, transport method, and declaration procedure.
For more detailed preparation, see Documents Required for Shipping from China to UAE.
Free Zone Gate Passes and Warehouse Handover
Importers should also distinguish customs clearance from physical delivery permission.
A shipment may have completed the required declaration procedure but still need a warehouse appointment, vehicle authorization, or unloading arrangement.
Before dispatch, verify the receiving address, gate entry requirements, contact person, and permitted delivery schedule.
For full-container shipments, confirm whether the warehouse can receive a loaded container, whether unloading labor or equipment is provided, and who handles empty-container return.
For machinery and heavy cargo, identify any site restrictions and specialized lifting requirements.
These details should be included in the agreed delivery scope rather than left to the truck driver on arrival.
What Happens When Goods Move from a UAE Free Zone to Mainland?
A free zone-to-mainland movement is a critical customs checkpoint.
Goods originally received under a free zone arrangement cannot automatically be treated as goods already cleared for domestic circulation.
When they are released into the UAE domestic market, an appropriate import procedure may be required.
When Does Free Zone-to-Mainland Clearance Apply?
Common situations include:
- A JAFZA distributor selling stored products to a Dubai mainland customer.
- Equipment leaving a free zone warehouse for installation at an Abu Dhabi project.
- Regional stock being allocated to a UAE retailer.
- A trading company releasing part of its stored inventory for domestic distribution.
The exact procedure depends on the goods’ existing customs status, the importer, the destination, and the competent customs authority.
A commercial sale and a physical customs movement are not necessarily the same event, and they must not be assumed to have identical VAT consequences.
Step-by-Step: Free Zone to Mainland Customs Procedure
1. Identify the goods being released
Confirm the product descriptions, quantities, HS codes, commercial values, and warehouse inventory references.
For a partial release, distinguish the goods leaving the free zone from the stock remaining under the original arrangement.
2. Confirm the mainland importer
Identify the entity eligible to make the required import declaration and confirm its customs registration.
Where appropriate, the importer appoints an authorized customs broker.
3. Select the correct declaration
The responsible customs representative confirms the applicable procedure.
Dubai Customs has identified an “Import to Local from Free Zone” declaration category in its published guidance.
The current declaration requirements should be confirmed with the relevant customs authority before submission.
4. Prepare supporting documentation
Depending on the procedure, supporting records may include:
- Delivery advice.
- Commercial invoice.
- Packing list.
- Relevant warehouse or stock records.
- Permits for restricted goods, where required.
Additional documents may apply.
5. Determine applicable customs duty and VAT treatment
The customs authority assesses the declaration and relevant duty requirements.
VAT must be considered under the applicable import and supply rules, which are separate from the customs duty assessment.
6. Obtain the required authorization
Customs may verify documents, inspect goods, or request further approvals.
Goods should not be dispatched into domestic circulation until the necessary authorizations have been obtained.
7. Arrange mainland transportation
The approved cargo movement is coordinated with the free zone operator, local transporter, and mainland receiving company.
Gate exit arrangements and delivery appointments must be completed.
8. Retain the transaction records
Keep the applicable declaration, invoice, tax records, delivery confirmation, and warehouse inventory adjustments.
These records are particularly important for partial releases from a larger shipment.
For further detail on ordinary import procedures, see Customs Clearance in UAE.
Who Pays Duty, VAT and Final Delivery Costs?
Three responsibilities should be addressed separately.
Legal customs responsibility depends on the party entitled or required to make the declaration and meet the applicable statutory obligations.
Contractual cost responsibility depends on the agreed sales and logistics contracts, including the chosen Incoterm.
Operational delivery responsibility depends on which party arranges transport, receiving appointments, unloading, and cargo handover.
An Incoterm can allocate commercial responsibilities, but it does not grant a seller or freight forwarder a customs registration or importing authorization.
For example, a DDP arrangement must still be structured around an eligible importer and legally valid import process.
Before confirming delivery terms, establish exactly who will file declarations, bear applicable charges, and resolve customs or warehouse exceptions.
Does Free Zone Delivery Mean No Customs Duty or VAT?
No. Free zone delivery does not automatically eliminate customs duty or VAT.
The treatment of a shipment depends on the applicable customs regime and the relevant tax rules.
Customs Duty and VAT Are Different
Customs duty is assessed under the relevant customs legislation, tariff classification, valuation, and import procedure.
VAT applies under a separate legal framework governing supplies and imports.
Goods may be subject to particular customs relief or suspension arrangements without every related transaction being exempt from VAT.
Likewise, a transaction that qualifies for special VAT treatment does not necessarily eliminate all customs obligations.
The terms “free zone,” “customs-controlled,” “bonded,” and “VAT-exempt” should not be used interchangeably.
What the FTA Says About VAT Designated Zones
Under Article 51 of the UAE VAT Executive Regulation, a VAT Designated Zone must meet specific conditions to receive the prescribed treatment.
The area must have defined boundaries and appropriate security and customs controls.
It must also maintain procedures governing the keeping, storage, and processing of goods, and the operator must comply with FTA requirements.
The FTA’s October 2, 2026 public clarification further explains that businesses should check the official List of Designated Zones and verify the relevant area with the free zone authority.
Even where those conditions are satisfied, the nature of the transaction remains critical.
| Transaction | VAT Consideration |
|---|---|
| Goods received into a qualifying VAT Designated Zone | Special treatment may apply subject to the relevant statutory conditions |
| Goods supplied within a Designated Zone | Treatment depends on the transaction and applicable exceptions |
| Goods intended for consumption or use | May be treated as supplied within the UAE for VAT purposes |
| Goods transferred between qualifying Designated Zones | Special treatment requires compliance with the applicable transfer and customs suspension conditions |
| Goods moved to UAE mainland | Import VAT and related transaction rules must be assessed |
| Goods delivered outside the UAE | Supporting commercial and customs evidence may be necessary |
| Warehousing and other services | Generally subject to normal place-of-supply rules, subject to specific exceptions |
The law also contains provisions for certain goods delivered outside the UAE and for goods moved into mainland where the supplier retains the prescribed evidence.
These provisions should not be interpreted as a blanket VAT exemption.
Why VAT May Arise When Goods Enter Mainland
When goods move from a qualifying VAT Designated Zone into UAE mainland, the movement may give rise to import VAT obligations.
The treatment depends on the importer, the underlying transaction, and the relevant statutory provisions.
For an eligible VAT-registered importer, the applicable import VAT may be accounted for through the prescribed reporting mechanism.
In other situations, payment may be necessary as part of the import process.
The VAT treatment of a related sale should also be considered separately.
Import VAT may be recoverable where the legal conditions for input tax recovery are satisfied, but recovery should not be assumed for every importer or transaction.
Three VAT Questions to Confirm Before Shipping
1. Is the actual warehouse inside a qualifying VAT Designated Zone?
Check the exact location against the official list and confirm the zone’s qualifying conditions with the relevant authority.
2. What is the intended use of the goods?
Goods stored for onward resale, goods used or consumed, and goods transferred into mainland may have different VAT consequences.
3. What evidence supports the intended treatment?
Confirm the necessary customs declarations, commercial records, inventory information, and proof of delivery or export.
The FTA’s current guidance and legislation should be reviewed whenever the transaction involves a potentially significant VAT exposure.
Which Delivery Destination Fits Your Business Model?
The most practical destination is not always the one closest to the arrival port.
It is the arrangement that supports the intended use of the goods with appropriate customs authorization, manageable cost, and reliable receiving arrangements.
Direct Mainland Import for Local Distributors
For a distributor whose inventory is intended for UAE domestic sales, direct mainland import may offer the simplest cargo flow.
It avoids creating an unnecessary intermediate warehouse movement where no regional storage function is needed.
The importer must still have the required registration, approvals, and delivery arrangements.
Free Zone Storage for Regional Distributors
A regional distributor may benefit from a free zone warehouse if inventory is allocated across multiple markets.
This can support order consolidation and staged dispatches.
However, the cost of storage, handling, subsequent customs procedures, and onward transportation should be considered before choosing this arrangement.
Regional Re-export Warehouses for Multinational Companies
An established multinational or regional trading business may use an eligible free zone facility to store goods before international distribution.
The warehouse could be operated by the company itself or an independent logistics service provider.
The critical requirements are an authorized receiving arrangement, accurate stock records, and proper customs documentation for each movement.
Hybrid Distribution for UAE and International Customers
Some distributors need both domestic and overseas fulfillment.
For example, a company may receive a consolidated shipment from China, release part of the stock into UAE mainland, and export the remainder to other countries.
This approach can provide flexibility but requires careful inventory allocation and separate handling of the relevant customs movements.
Destination Selection Matrix
| Business Model | Suggested Starting Arrangement | Main Benefit | Key Requirement |
|---|---|---|---|
| UAE wholesale importer | Direct mainland import | Direct delivery to domestic inventory | Eligible importer and customs clearance |
| Local engineering project buyer | Mainland import and site delivery | Goods move toward their intended use | Product approvals and site receiving |
| Regional distributor | Authorized free zone storage | Flexible allocation across markets | Warehouse and customs status verification |
| Multinational re-export operation | Free zone storage plus onward export | Centralized regional inventory | Reliable stock and exit documentation |
| Mixed domestic and international sales | Free zone storage with partial releases | Separate allocation by market | Multiple customs and VAT checkpoints |
These are planning recommendations, not guarantees of customs eligibility or tax treatment.
How to Compare the Total Cost of Mainland and Free Zone Delivery
The lowest initial customs or freight cost does not necessarily produce the lowest overall supply chain cost.
The correct comparison should cover the full cargo journey.
| Cost Component | Direct Mainland Delivery | Free Zone Storage and Later Movement |
|---|---|---|
| International freight | Freight from China to UAE gateway | Freight from China to UAE gateway |
| Terminal and carrier charges | Applicable arrival and release charges | Applicable arrival and release charges |
| Customs processing | Domestic import procedure | Free zone entry and later applicable procedures |
| Customs duty | Depends on the domestic import | Depends on goods and subsequent movements |
| VAT | Applicable import and supply treatment | Depends on zone status and transactions |
| Local transportation | Gateway to domestic receiver | Gateway to free zone plus onward movement |
| Storage | Based on business requirements | Warehouse charges may apply |
| Handling | Unloading and local services | Additional receiving, storage and dispatch operations |
| Re-export documentation | If subsequently exported | If goods are exported from the zone |
Illustrative Example: 100 Cartons for Two Markets
Assume a regional trading company purchases 100 cartons of commercial inventory from China.
The company intends to allocate:
- 40 cartons to UAE mainland customers.
- 60 cartons to buyers outside the UAE.
These numbers are illustrative only.
Option A: Direct Mainland Import
The company imports the goods for domestic circulation and subsequently arranges exports for overseas orders.
The full import transaction and later export transactions must be evaluated under the relevant customs and tax rules.
Option B: Free Zone Storage and Partial Release
The company receives the goods under an appropriate free zone arrangement.
Forty cartons are later released to mainland through the required customs procedure.
Sixty cartons remain under the relevant storage arrangement until they are shipped overseas.
The company must account for the additional storage, inventory handling, and customs documentation.
A useful comparison is:
Total Route Cost = International Freight + Terminal Charges + Customs Processing + Storage + Handling + Local or Onward Transport + Applicable Taxes and Other Charges
For customs duty estimates:
Applicable Duty = Assessable Customs Value × Verified Duty Rate
Actual calculations must use the correct HS classification, valuation basis, and applicable legal treatment.
Recoverable VAT, temporary deposits, and financial guarantees should be distinguished from permanent logistics expenses.
This comparison should be based on actual quotations and transaction information, not generic claims that one route is always cheaper.
Free Zone Delivery Planning Checklist
Use this checklist before cargo leaves China.
Destination and Cargo Use
- Confirm whether the goods are intended for mainland use, free zone storage, or re-export.
- Obtain the complete delivery address.
- Identify the actual customs jurisdiction of the receiving facility.
- Verify any claimed VAT Designated Zone status.
- Confirm whether some inventory will later enter UAE mainland.
Consignee and Customs Responsibilities
- Confirm the legal consignee and receiving company.
- Identify the eligible importer or exporter for the intended procedure.
- Verify relevant customs registration and authorization.
- Identify the appointed customs broker or representative.
- Agree who will prepare and submit the required declarations.
Cargo and Shipping Documents
- Check commercial invoice details.
- Verify packing list quantities, weights, and dimensions.
- Confirm the bill of lading or air waybill instructions.
- Review the goods description and HS classification.
- Identify product-specific permits or approvals where required.
- Confirm whether additional free zone entry or receiving documents are needed.
Warehouse and Final Delivery
- Obtain warehouse receiving confirmation.
- Confirm gate-access and vehicle requirements.
- Arrange any necessary delivery appointment.
- Confirm unloading capability and responsibility.
- Clarify container return, waiting time, and possible additional charges.
- Identify who will acknowledge receipt and report discrepancies.
Tax and Onward Distribution
- Review applicable duty and VAT questions with qualified local parties.
- Confirm the procedure for any later mainland release.
- Establish inventory records for partial releases.
- Confirm the customs requirements for onward export.
- Retain the prescribed shipping, customs, and tax evidence.
Completing these checks before departure can reduce the risk of having goods arrive at a UAE gateway without a workable release or receiving arrangement.
Common Mistakes That Cause Delivery Problems
Using a General Location Instead of an Exact Warehouse Address
Instructions such as “deliver to JAFZA” or “deliver to KEZAD” may be insufficient.
The shipping and receiving parties need the specific facility, legal consignee, and customs arrangements.
Assuming Free Zone Delivery Means Automatic Tax Exemption
A commercial free zone designation does not determine the VAT treatment of every transaction.
The actual area, movement, and statutory conditions must be verified.
Naming a Warehouse as the Customs Importer Without Authorization
A facility that can physically receive goods may not be the entity eligible to make the required customs declaration.
The parties should confirm the legal importer and declarant before issuing the final shipping documents.
Moving Goods to Mainland Without the Correct Procedure
Inventory held under a free zone arrangement may require a separate domestic import declaration before release into mainland.
The procedure should be planned before the warehouse dispatches the goods.
Assuming a Delivery Order Means Customs Clearance Is Complete
Carrier release, customs authorization, terminal release, and warehouse entry may involve different processes.
All relevant requirements must be completed before the intended movement.
Ignoring Warehouse Access and Unloading Requirements
A successful international freight booking does not guarantee that the receiving site can accept the truck or container.
Unloading equipment, access permissions, working hours, and empty-container return arrangements should be confirmed in advance.
Failing to Retain Re-export Evidence
Incomplete records can create difficulties in demonstrating how goods moved through the UAE.
Maintain the appropriate customs, transportation, commercial, and inventory records.
Can a Mainland UAE Company Receive Cargo at a Free Zone Warehouse?
A mainland company may be able to arrange storage or receiving through an appropriately authorized free zone operator, depending on the arrangement and applicable customs procedures. However, the ability to use a warehouse does not automatically authorize the company to make every type of free zone declaration. Confirm the importer, consignee, warehouse agreement, and customs responsibilities before shipping.
Are All Dubai South and KEZAD Warehouses VAT Designated Zones?
No. Facilities within the wider Dubai South or KEZAD developments may operate under different customs and regulatory arrangements. VAT Designated Zone status must be verified for the specific area using the FTA's official list and the relevant qualifying conditions. The receiving company should obtain confirmation from the appropriate free zone authority.
Can I Store Goods in JAFZA and Later Release Only Part of the Shipment to UAE Mainland?
Partial release may be possible under the applicable customs and warehouse arrangements. The quantities entering mainland must be properly identified, declared, and released. The remaining goods should retain appropriate inventory and customs-status records. Duty and VAT implications must be assessed for the actual movement rather than assumed from the original free zone entry.
Does a Shipping Line’s Delivery Order Mean the Goods Are Customs-Cleared?
No. A delivery order generally concerns the carrier's release of cargo. It does not replace the customs declaration or any required customs authorization. The shipment may also be subject to terminal release, inspection, free zone entry, or warehouse access requirements. Confirm all outstanding steps before arranging final delivery.
What Documents Help Prove Goods Were Re-exported from a UAE Free Zone?
Relevant evidence may include the applicable export or re-export declaration, commercial invoice, transport documents, inventory movement records, and customs exit confirmation. The precise requirements depend on the customs procedure and any tax treatment being claimed. Confirm which evidence must be retained with the relevant authority or qualified adviser.
Plan Your Mainland, Free Zone or Re-export Shipment
Choosing between mainland delivery and free zone receiving is ultimately a decision about the entire cargo movement—not just where the truck will unload.
For shipments from China, the most effective approach is to establish the intended final market, receiving company, customs responsibilities, and warehouse arrangements before the goods depart.
Winsail helps businesses plan international freight from China to the UAE and review suitable transportation and delivery arrangements for mainland destinations, free zone receiving, and onward regional distribution, subject to applicable local services and approvals.
To prepare a practical shipping plan, share the following information:
- Origin in China: Supplier city and pickup location.
- Cargo details: Product description, quantities, weight, CBM, and packaging.
- Commercial information: Cargo value and agreed Incoterm.
- UAE destination: Full address, including free zone or mainland status.
- Receiving party: Consignee company, warehouse contact, and available broker information.
- Intended goods movement: Domestic sale, project delivery, storage, partial mainland release, or re-export.
- Shipment schedule: Cargo-ready date and required delivery timeframe.
With this information, Winsail can review the international freight requirements, identify the necessary destination-side coordination, and help you prepare a shipment plan aligned with the intended cargo flow.
Regulatory Sources and Information Scope
This guide focuses on commercial goods exported from China to UAE mainland, free zones, and onward re-export arrangements. Regulatory information was checked on November 13, 2026.
Official references:
- UAE Federal Tax Authority — Free Zones and Designated Zones for Tax Purposes (TAXP010, October 2026)
- UAE Federal Tax Authority — VAT Executive Regulation and Amendments, including Article 51
- Dubai Customs — Customs Declaration Services
Disclaimer: This article provides general logistics planning information and does not constitute legal, customs, or tax advice. Actual requirements depend on the goods, importer, customs jurisdiction, receiving facility, declaration procedure, and applicable regulations. Confirm transaction-specific requirements with the relevant UAE customs authority, free zone operator, authorized customs broker, and qualified tax adviser. Customs approval, tax outcomes, and the availability of particular destination-side services cannot be guaranteed.
